Pennsylvania's tropical storm history
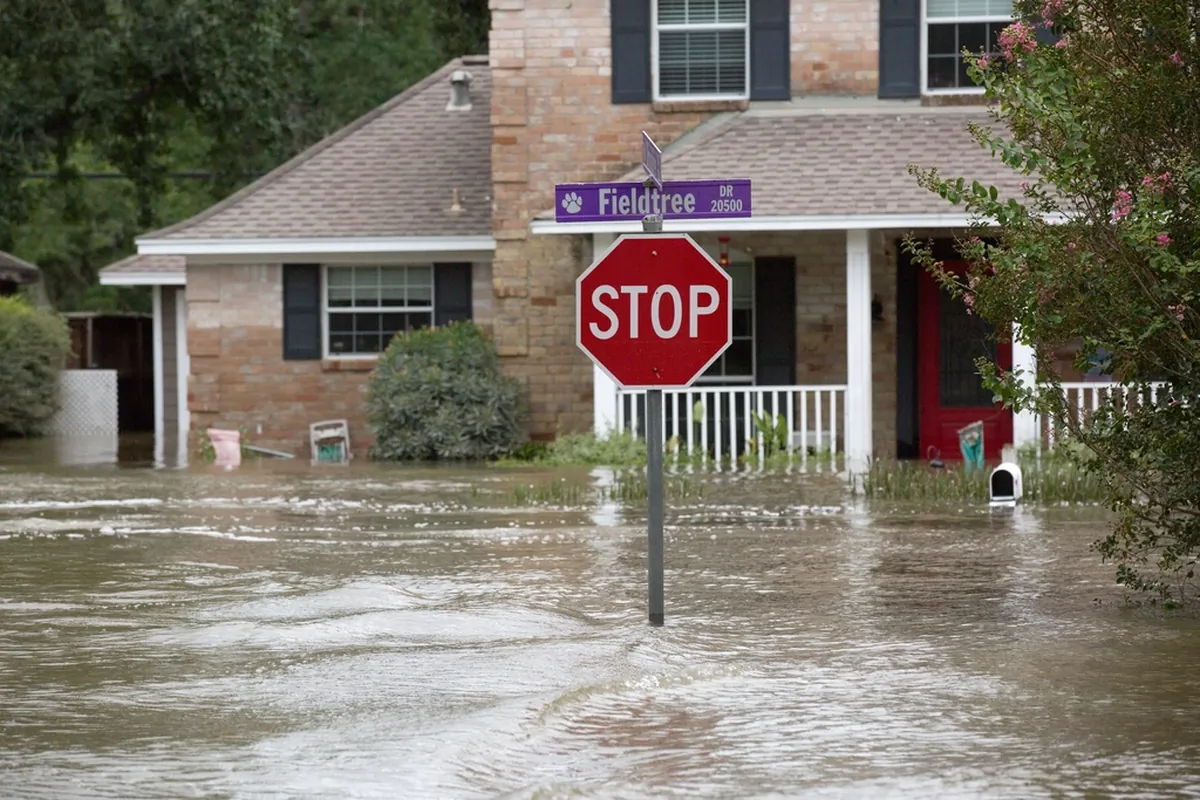
The state's worst tropical events have mostly been water events. Hurricane Agnes in June 1972 sent the Susquehanna through Wilkes-Barre and Harrisburg. The remnants of Ivan in September 2004 flooded communities around Pittsburgh. Tropical Storm Lee in September 2011 swamped Bloomsburg, while the Wilkes-Barre levee held. Superstorm Sandy in October 2012 brought widespread wind damage and outages. The remnants of Ida on September 1, 2021 flooded the Schuylkill through Philadelphia and Manayunk and spawned a tornado in Montgomery County. The remnants of Debby in August 2024 caused flash flooding in Tioga County.
Each of those storms left owners sorting damage into separate buckets, and each bucket can be governed by a different policy.
The split that drives every remnant claim
| Source of damage | Where it is usually handled |
|---|---|
| Rising surface water, overflowing creeks and rivers | Flood policy (NFIP or private); excluded from standard homeowner forms |
| Rain entering through a wind-damaged roof or wall | Often the property policy, subject to its terms |
| Fallen trees on the structure | Usually the property policy |
| Sewer or drain backup | Often only with a specific endorsement |
| Groundwater seeping through foundation walls | Frequently excluded or limited |
Pennsylvania has no state wind pool. Owners who cannot find coverage in the regular market may be insured through the Pennsylvania FAIR Plan, which has its own policy terms.
How appraisal fits a mixed loss
Appraisal under a property policy values the damage that policy covers. If your basement flooded from the creek and wind also opened your roof, the homeowner panel generally values the roof and interior rain damage, while the flood claim follows its own process. Keeping those scopes cleanly separated is where careful documentation pays off: a ceiling stain on the second floor is a very different claim than a waterline on basement drywall.
Documenting a remnant storm
- Photograph water lines, roof openings and tree strikes before cleanup where it is safe.
- Note the timing: when rain entered, when the creek rose, when power failed.
- Keep receipts for drying, tarping and emergency tree work.
- Save any National Weather Service reports or local news covering your area.
Where we work after these storms
River towns along the Susquehanna, the Lehigh and the Schuylkill see these claims most often, along with hillside communities where runoff and falling trees do the damage. Our Wilkes-Barre and Philadelphia pages describe local flood and storm patterns. Keep the property policy's suit-limitation clause in mind too; many set one year from the date of loss.
Frequently asked questions
Does my homeowner policy cover flooding from hurricane remnants?
Standard homeowner policies exclude flood. Flood damage is generally handled through an NFIP or private flood policy, while wind and wind-driven rain damage may fall under the homeowner policy.
Can one appraisal resolve both my flood and homeowner claims?
Usually not. Each policy has its own terms and process. A homeowner appraisal values the damage covered by that policy, and the flood claim proceeds separately.
Is there a hurricane deductible in Pennsylvania?
Some policies sold in Pennsylvania include a separate wind or named-storm deductible, while many do not. Check your declarations page to see which deductible applies.