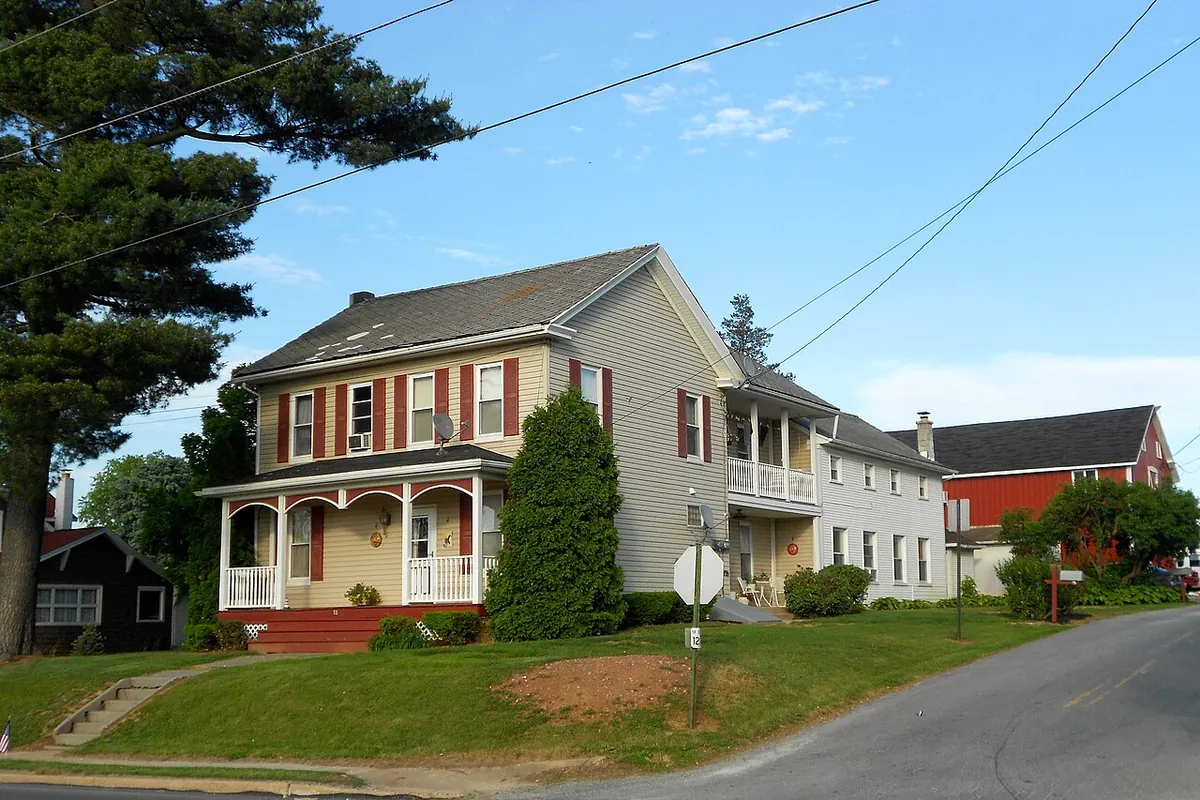
A claim on a 1920s brick twin in Allentown is not the same job as a claim on a 2015 vinyl-sided colonial in Cranberry Township. Yet carrier estimates often treat them alike, with generic materials, thin labor allowances and little room for the details that make older homes what they are. Our homeowner appraisal work starts from the house you actually own.
Housing we see across the state
Rowhomes and twins
Philadelphia, Reading, York and Harrisburg are full of attached homes with flat modified-bitumen roofs and shared party walls. Water and smoke rarely stay on one side of that wall, and a repair on one roof often has to tie into the neighbor's. We scope those transitions instead of ignoring them. Our rowhome and flat roof guide covers the common sticking points.
Stone farmhouses and older detached homes
In Lancaster, Berks and Chester counties, fieldstone walls, deep window returns and plaster on lath are common. Matching stone, mortar and plaster is slow, skilled work, and it should be priced that way.
Victorians and hillside brick
Scranton and Erie have large Victorian homes with complex rooflines and wood trim. Pittsburgh's hillside neighborhoods have brick homes where access, staging and steep lots add real cost. See our Pittsburgh page for local notes.
How a homeowner appraisal unfolds
- We review your policy, the insurer's estimate and any payments already issued.
- We inspect the home, measure every affected area and photograph conditions.
- We build an independent estimate and compare it line by line with the carrier's.
- If appraisal is demanded, we serve as your appraiser and work toward a signed award.
What appraisal can and cannot settle
A panel sets the amount of loss. It can decide how much a damaged slate roof costs to repair, or whether the hardwood in a hallway can be matched. It generally does not decide whether a loss is covered in the first place. Flood, for example, is excluded from standard homeowner policies and handled through NFIP or private flood coverage. Earth movement is usually excluded too, which is why many owners in coal regions carry separate Mine Subsidence Insurance through the Pennsylvania Department of Environmental Protection.
Timing matters
Many Pennsylvania homeowner policies include a suit-limitation clause, commonly one year from the date of loss. Appraisal may not stop that clock, so if a lawsuit is even a possibility, speak with a Pennsylvania attorney early. If you have questions about how the insurer handled your claim, the Pennsylvania Insurance Department accepts consumer complaints.
A homeowner appraisal works best when everyone agrees the loss is covered and the fight is over dollars. If that describes your claim, a phone call is usually enough for us to tell you whether appraisal looks worthwhile.
Frequently asked questions
Is appraisal worth it on a smaller homeowner claim?
It depends on the size of the gap and the appraisal costs your policy assigns to each side. If the difference is modest, a detailed estimate review may resolve it without a full panel.
Will the appraisal panel consider matching for my older home?
The panel prices what the policy covers. Where your policy and the facts support replacing materials so the repair reasonably matches, the appraisers can include that in the amount of loss.
Can I stay in my home while the appraisal is underway?
Usually yes, unless the damage makes it unsafe. If you are displaced, additional living expense is part of most homeowner policies and can also be disputed if the amount is the issue.